Fed Holds Rates at 3.75%-4%: What It Means for Your Money
The Fed left interest rates unchanged on Oct. 28, 2026, in a 10-2 vote as Lisa Cook dissented. Here's what it means for mortgages, credit cards, savings and a December hike.

The short answer
The Federal Reserve kept its benchmark federal funds rate in a target range of 3.75% to 4% on Wednesday, Oct. 28, 2026, in a 10-2 vote. Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented, both preferring a quarter-point hike. The Fed said inflation 'remains elevated' and that it wants more information before its next move. Futures markets point to a strong chance of a rate hike at the next meeting, Dec. 8-9. For households, credit card rates are likely to keep rising, 30-year mortgage rates remain above 7%, and top high-yield savings accounts still pay more than 4%.
Key takeaways
- The Fed held the federal funds rate at 3.75% to 4%, where it has been since a quarter-point hike in September.
- The vote was 10-2: Lisa Cook (her first dissent) and Beth Hammack wanted a 0.25-point hike.
- The Fed upgraded the economy to 'expanding at a strong pace' and said inflation 'remains elevated.'
- Next meeting: Dec. 8-9, 2026. Futures pricing suggests a strong possibility of a hike then.
- Chair Kevin Warsh said one 2027 meeting will focus only on strategy, with no rate vote.
In this article
The Federal Reserve left interest rates unchanged on Wednesday, Oct. 28, 2026, keeping the federal funds rate in a target range of 3.75% to 4%. The decision was widely expected, but the vote was not unanimous: Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented in favor of a quarter-point hike, the Fed's statement shows. The Fed rate decision was one of the top U.S. stories on Google News overnight. Here's what the Fed decided, why it matters and what it means for your mortgage, credit card and savings.
Not financial advice. This article explains the Federal Reserve's published decision and reporting on its likely effects. Talk to a qualified professional about your own situation.
What the Fed decided on Oct. 28
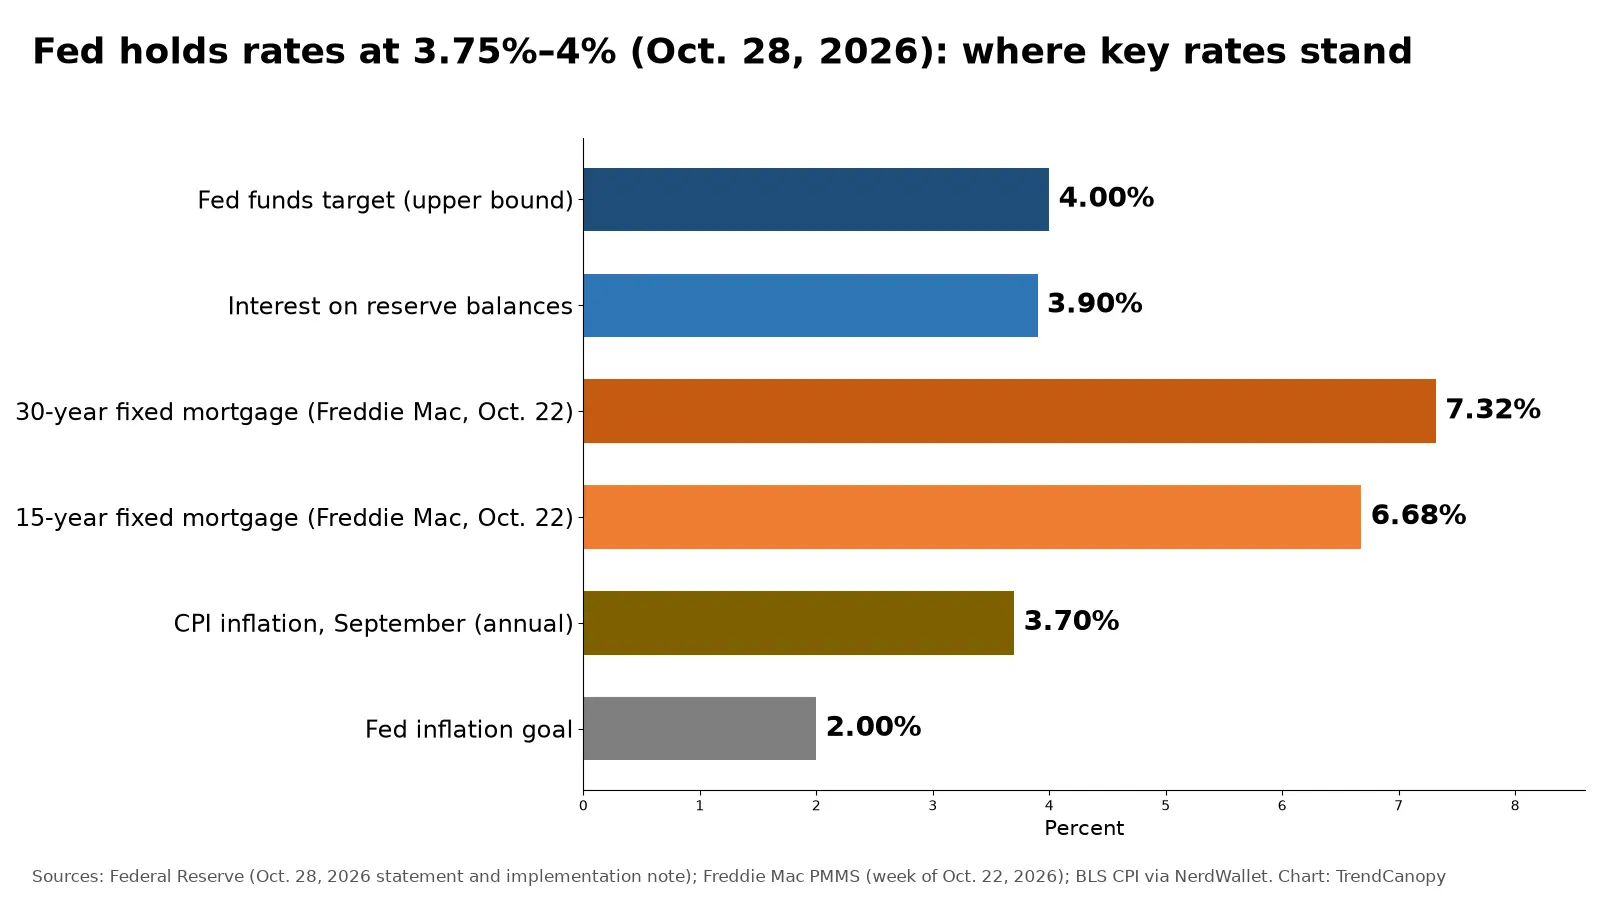
The Federal Open Market Committee (FOMC) voted 10-2 to hold its benchmark rate at 3.75% to 4%, where it has been since a quarter-point increase in September, CNBC reported. In its implementation note, the Fed also kept the interest rate it pays banks on reserve balances at 3.90%, effective Oct. 29.
The policy statement made three points worth knowing:
- The economy is "expanding at a strong pace." That is an upgrade from "solid" in September, Axios noted. The Fed also said job gains have kept pace with the workforce and the unemployment rate "has changed little."
- "Inflation remains elevated." The Fed's goal is 2%. Inflation has been above that target for more than five years, according to CNBC.
- The Fed is waiting for data. "The accumulation of more information will help the Committee determine the policy stance appropriate to ensure a timely return of inflation to the Committee's 2 percent goal," the statement said.
In short, the Fed paused rather than raised rates, but it did not signal that it is done tightening.
Why Lisa Cook's dissent made headlines
Dissents by Washington-based Fed governors have historically been rare, though that norm has broken down since 2024, according to Axios. This was Cook's first dissent since joining the Fed's Board of Governors in 2022 as an appointee of President Joe Biden, CNBC reported.
Her vote drew extra attention because Cook is the governor President Donald Trump has been trying to remove over allegations about information on home loan applications. The Supreme Court stopped an earlier attempt, and the administration has restarted the effort with a White House hearing scheduled for early November, according to CNBC. Her lawyers say the allegations are a pretext, Axios reported. Asked whether he or the Fed would take part in that hearing, Chair Kevin Warsh said, "Not to my knowledge."
Hammack, a consistently hawkish voice, also dissented in July for the same reason. Dallas Fed President Lorie Logan and Minneapolis Fed President Neel Kashkari, who dissented alongside her in July, joined the majority this time, CNBC said.
Is a rate hike coming in December?
The next FOMC meeting is Dec. 8-9, 2026, according to the Fed's meeting calendar. It is a meeting that includes a new Summary of Economic Projections, often called the "dot plot."
Markets think a hike is possible. Futures pricing indicates a strong possibility of another hike in December, and perhaps one or two more in 2027, CNBC reported. Before Wednesday's decision, traders had priced in less than a 10% chance of an October hike, according to the CME Group's FedWatch tool.
Key data between now and then will shape the call:
- PCE inflation, the Fed's preferred gauge, for September is due Thursday, Oct. 29. CNBC said it is expected to be above 3% even excluding food and energy.
- Consumer prices. September's Consumer Price Index showed annual inflation rising to 3.7%, NerdWallet noted.
- Growth. The Atlanta Fed's GDPNow tracker points to 3.4% annualized growth in the third quarter, which would be the strongest in a year, according to CNBC.
Warsh has avoided giving forward guidance about the Fed's next steps. Politics are also in the background: the midterm elections are Nov. 3, and some observers have speculated that officials would be reluctant to raise rates so close to a vote, CNBC reported. For voting dates and deadlines, see our 2026 midterms early voting guide.
What the Fed decision means for your money
The federal funds rate is what banks charge each other for overnight loans, but it ripples into many consumer rates. Because the Fed held steady and more hikes may be coming, consumers are unlikely to see much relief from high borrowing costs soon, CNBC's personal finance team reported.
Credit cards
Most credit cards have variable rates tied to the prime rate, which is generally about 3 percentage points above the Fed's benchmark. Changes usually show up within one or two billing cycles. Average card rates have risen for three straight months and are at their highest since December 2025, LendingTree's Matt Schulz told CNBC, adding that rates are "highly likely to rise in the next few months, too, as card issuers implement the Fed's September hike."
What you can do: Paying down variable-rate balances, or asking your issuer for a lower rate, matters more than usual when rates are rising.
Mortgages
Fixed mortgage rates don't move in lockstep with the Fed. They generally track long-term Treasury yields and inflation expectations. Freddie Mac's 30-year fixed average was 7.32% for the week of Oct. 22, down from 7.40% a week earlier but well above 6.19% a year ago. The 15-year fixed averaged 6.68%, according to Freddie Mac. Freddie Mac publishes a new weekly average on Thursdays at noon ET.
NerdWallet's Zillow-based weekly average slid to 7.17% APR in the week ending Oct. 28, and NerdWallet warned that hotter inflation data could push rates higher in November. If you're weighing a refinance or PMI changes, our explainer on the White House mortgage executive order covers what changed.
Savings accounts and CDs
Savings yields tend to follow the Fed's rate, so a hold keeps them largely steady. Some top online high-yield savings accounts still pay more than 4%, according to Bankrate data cited by CNBC. That is far more than a typical savings account at a big bank.
Car loans, student loans and other debt
Variable-rate loans and home equity lines of credit generally move with the prime rate, so they won't change from this decision alone. Fixed-rate auto loans and existing federal student loans keep the rate you locked in. If you have defaulted federal loans, see how student loan debt collection is working this year.
Warsh changes the Fed's meeting schedule
The other news from Warsh's press conference: the Fed will reshape its calendar. "We believe eight meetings per year is the right number for the FOMC, but in 2027, one meeting will focus exclusively on broad monetary policy strategy, with neither a vote on the federal funds rate nor a policy statement anticipated," Warsh said, as quoted by CNBC. He said he expects two strategy meetings and six rate-setting meetings in 2028.
That means fewer chances each year for the Fed to change rates, which could make each decision a bigger market event.
What's next
- Oct. 29: September PCE inflation data is released.
- Early November: White House hearing on Lisa Cook's potential removal.
- Nov. 3: Midterm elections.
- Nov. 18: Minutes of the October meeting are due, three weeks after the decision, per the Fed's usual schedule.
- Dec. 8-9: Next FOMC meeting and new economic projections.
The bottom line
The Fed hit pause in October, not stop. With inflation at about 3.7% and the economy growing strongly, two officials already want higher rates, and markets see a real chance of a December hike. For now, expect pricier credit card debt, mortgage rates above 7% and solid savings yields. For more money news, see the latest on Microsoft's voluntary buyouts.
Frequently asked questions
- Did the Fed raise interest rates in October 2026?
- No. On Oct. 28, 2026, the Federal Open Market Committee voted 10-2 to keep the federal funds target range at 3.75% to 4%. Two members, Governor Lisa Cook and Cleveland Fed President Beth Hammack, voted for a quarter-point increase instead.
- What is the federal funds rate right now?
- The target range is 3.75% to 4%, effective Oct. 29, 2026. The Fed also kept the interest rate it pays banks on reserve balances at 3.90%, according to its implementation note. AP describes the key rate as about 3.9%.
- Why did Lisa Cook dissent?
- Cook preferred to raise the target range by a quarter percentage point, the Fed's statement says. It was her first dissent since joining the Board of Governors in 2022, CNBC reported. She is also the governor President Trump is seeking to remove, with a White House hearing on that scheduled for early November.
- When is the next Fed meeting?
- The next scheduled FOMC meeting is Dec. 8-9, 2026, with a rate decision expected on Dec. 9. It is one of the meetings that comes with a Summary of Economic Projections, the Fed's calendar shows.
- Will mortgage rates go down after the Fed decision?
- Not directly. Fixed mortgage rates track long-term Treasury yields and inflation expectations more than the Fed's overnight rate. Freddie Mac's 30-year fixed average was 7.32% for the week of Oct. 22, 2026, down from 7.40% a week earlier but above 6.19% a year ago.
- Will credit card interest rates go up?
- Probably. Most cards have variable rates tied to the prime rate, and LendingTree's Matt Schulz told CNBC rates are highly likely to keep rising as issuers implement September's hike.
Sources
- Federal Reserve issues FOMC statement · Federal Reserve Board, Oct. 28, 2026
- Implementation Note issued October 28, 2026 · Federal Reserve Board, Oct. 28, 2026
- Meeting calendars and information · Federal Open Market Committee
- Fed holds rates steady amid ongoing concerns over inflation · CNBC, Oct. 28, 2026
- Fed rate decision: What it means for your money · CNBC, Oct. 28, 2026
- Fed keeps key rate unchanged at about 3.9% despite elevated inflation · Associated Press, Oct. 28, 2026
- Fed leaves rates steady as governor Lisa Cook dissents · Axios, Oct. 28, 2026
- Primary Mortgage Market Survey · Freddie Mac, Oct. 22, 2026
- As Fed Holds Steady, Are 7.5% Mortgage Rates Still Possible? · NerdWallet, Oct. 28, 2026
About the author
Editorial team
The TrendCanopy editorial team researches what Americans are searching for, checks the facts against primary sources and publishes clear, sourced explainers.
Spotted an error? Read our corrections policy or contact us. Last reviewed October 29, 2026.
Related stories
Student Loan Debt Collection: What Borrowers Should Know
Reports say collections on defaulted federal student loans could restart, which the Education Department disputes. What's official and what to do.
Trump Mortgage Executive Order: What It Changes for PMI
The Oct. 22 housing order targets mortgage insurance, refinance title costs and USDA and VA loan rates. What it does, what it doesn't and when it applies.
SSI November 2026 Payment Comes Oct. 30: What to Know
There's no SSI payment in November: it arrives early on Oct. 30. Here's the full payment schedule and what the 3.6% COLA for 2027 means for your check.