Trump Mortgage Executive Order: What It Changes for PMI
The Oct. 22 housing order targets mortgage insurance, refinance title costs and USDA and VA loan rates. What it does, what it doesn't and when it applies.

The short answer
President Trump signed an executive order on Oct. 22, 2026, titled "Decreasing Housing Costs for the American People." It asks the FHFA to set up a pilot that would cancel mortgage insurance proactively on eligible future Fannie Mae and Freddie Mac loans, to turn a title-insurance alternative for refinances into a permanent nationwide program, and directs USDA and VA to cut rates on their direct home loans. It does not cancel PMI on existing loans, and most changes require agency follow-up.
Key takeaways
- PMI: a proposed FHFA pilot for proactive cancellation, applying only to mortgages made after the pilot starts.
- Refinances: expands a pilot letting Fannie and Freddie accept automated title reviews instead of lender's title insurance.
- USDA and VA are told to reduce interest rates on single-family loans they make directly.
- A new Task Force on Manufactured Housing Innovation has 180 days to send recommendations.
- Existing PMI cancellation rules still apply: borrowers can ask their servicer now.
In this article
President Donald Trump signed an executive order on Oct. 22, 2026, aimed at lowering the costs of owning and refinancing a home. Titled "Decreasing Housing Costs for the American People," it targets private mortgage insurance (PMI), title insurance on refinances, USDA and VA direct-loan rates, and the rules for factory-built homes. Searches for "Donald Trump mortgage executive order" and "Trump refinance mortgage cost" climbed past 20,000 in a day on Google Trends as homeowners asked what changes for them. The short answer: some things could change, but not immediately, and not for every loan.
Not investment advice. This article summarizes the text of a federal executive order and reporting on it. Talk to your lender or servicer about your own loan.
What we know: the four main parts of the order
The order's stated purpose, in Section 1, is to "reduce regulatory barriers to mortgage origination and costs impeding homeownership," to "embrace innovative risk and value assessment technologies that incorporate Super Intelligence to drive down mortgage and homeownership costs," and to promote competition in the housing and mortgage market. It builds on an earlier order, Executive Order 14394 of March 13, 2026, on removing regulatory barriers to affordable home construction, which Section 3 cites.
| Section | What it directs | Who acts | Applies to |
|---|---|---|---|
| Sec. 2, mortgage insurance | A pilot to proactively cancel mortgage insurance when borrowers meet equity rules based on current market value | FHFA director, Fannie Mae, Freddie Mac | Only loans made after the pilot is set up |
| Sec. 3, manufactured housing | A Task Force on Manufactured Housing Innovation; recommendations within 180 days | HUD, FHFA (co-chairs), USDA, Commerce, VA | Factory-built homes in federal programs |
| Sec. 4, title insurance | Expand the title acceptance pilot into a permanent nationwide program for eligible refinances | FHFA director, Fannie Mae, Freddie Mac | Eligible refinances |
| Sec. 5, direct loans | Reduce interest rates on single-family loans made directly by USDA and VA | Agriculture and VA secretaries | USDA and VA direct loans |
Source: executive order text and White House fact sheet.
1. Proactive PMI cancellation, for future loans
Under Section 2, the FHFA director, if he determines it is in the best interests of Fannie Mae, Freddie Mac, the FHFA and the public, would direct the two companies to create a pilot. It would periodically review loans they own or guarantee, use automated valuation models to estimate current home values, and identify borrowers who appear to meet the equity and payment-history requirements for cancellation.
The White House fact sheet says the change "will eliminate a large monthly expense for qualifying Americans." But the order's text is explicit that the pilot is "applicable only to mortgages made after the establishment of the pilot program." Servicers would be asked to notify borrowers when insurance may be canceled and to reduce appraisal costs and paperwork, "to the extent permitted by law and operationally feasible."
Mortgage.news stresses the distinction: the order "does not cancel private mortgage insurance across existing mortgages."
2. Cheaper refinances through title alternatives
Section 4 targets closing costs. It asks the FHFA director to expand an existing title acceptance pilot into an ongoing, nationwide program at both Fannie Mae and Freddie Mac. On eligible refinances, the companies could accept an automated title review or other FHFA-approved title-risk assessment instead of a lender's title insurance policy.
In expanding it, the director must consider:
- Allowing loan-to-value ratios above the current 80% limit where title risk is low.
- Removing geographic limits and certifying more title-assessment providers.
- Waiving appraisals and income re-verification for limited cash-out refinances that lower a borrower's monthly payment.
- Reducing or eliminating loan-level price adjustments and other fees on these refinances.
Any savings must be passed through to borrowers, and lenders must tell borrowers about them.
3. USDA and VA direct-loan rates
Section 5 directs the Secretaries of Agriculture and Veterans Affairs to reduce interest rates on single-family home loans their departments make directly, consistent with the law and available appropriations. The order does not specify how much, and it cites the specific statutes that govern each department's direct-loan rates (42 U.S.C. 1490a and 38 U.S.C. 3762).
4. A task force on manufactured housing
Section 3 creates the Task Force on Manufactured Housing Innovation, co-chaired by the HUD secretary and the FHFA director. Within 180 days, it must recommend ways to make modern factory production of homes easier under federal programs, such as reciprocal recognition of inspections and certifications and removing duplicative reviews.
What the order does not do
- It does not cancel PMI on current loans. Today's rules still apply. Many borrowers can request cancellation when their balance reaches 80% of the home's original value, and it generally ends automatically at 78% if payments are current, according to the CFPB guidance cited by Mortgage.news.
- It does not set a start date. Each major change depends on the FHFA director or cabinet secretaries acting, and the order says it must be implemented "consistent with applicable law and subject to the availability of appropriations."
- It does not guarantee savings for any individual borrower. Eligibility rules have not been written.
HousingWire reported that the fact sheet was published and promoted before the final order text appeared on the White House website.
What borrowers can do now
Mortgage.news recommends that borrowers ask their servicer about current mortgage-insurance cancellation options instead of waiting for a future pilot, and that anyone considering a refinance get written lender and title quotes and compare total costs with expected savings. VA and USDA direct-loan borrowers should watch for announcements from those departments on any rate change.
What's next
- FHFA decisions. Watch for FHFA directives to Fannie Mae and Freddie Mac establishing the PMI pilot and the expanded title program.
- USDA and VA notices on new direct-loan interest rates.
- Task force report on manufactured housing, due within 180 days of Oct. 22, or by about late April 2027.
The bottom line
The order points federal housing agencies toward lower mortgage insurance and refinance costs, but it mostly sets direction rather than delivering immediate savings. If you pay PMI today, ask your servicer about the cancellation options that already exist. For more money news, see the SSI November payment schedule and 2027 COLA and what Microsoft's buyout offer means.
Frequently asked questions
- Does the executive order cancel my private mortgage insurance?
- No. The order asks the FHFA to have Fannie Mae and Freddie Mac set up a pilot that would apply only to mortgages made after the pilot is established. Existing loans keep the current cancellation rules, which let many borrowers request PMI cancellation at 80% of the home's original value, according to the CFPB as cited by Mortgage.news.
- When was the housing executive order signed?
- President Trump signed "Decreasing Housing Costs for the American People" on Oct. 22, 2026, according to the White House.
- Will refinancing get cheaper?
- Possibly, for eligible borrowers. The order directs the FHFA director, if he finds it in the public interest, to expand a pilot that lets Fannie Mae and Freddie Mac accept an automated title review instead of a lender's title insurance policy on eligible refinances, and requires that savings be passed to borrowers. No effective date was given.
- What does the order do for VA and USDA borrowers?
- It directs the Secretaries of Agriculture and Veterans Affairs to reduce interest rates on single-family home loans made directly by their departments, consistent with law and available funding. It does not set a specific rate.
Sources
- Decreasing Housing Costs for the American People (Executive Order) · The White House, Oct. 22, 2026
- Fact Sheet: President Donald J. Trump Decreases Housing Costs for Americans · The White House, Oct. 22, 2026
- New Housing Order Targets PMI, Refinance Title Costs and Manufactured Homes: What Changes Now? · Mortgage.news, Oct. 23, 2026
- Trump signs executive order targeting mortgage costs · HousingWire, Oct. 2026
- Executive Order: Decreasing Housing Costs for the American People · The American Presidency Project (UC Santa Barbara), Oct. 22, 2026
About the author
Editorial team
The TrendCanopy editorial team researches what Americans are searching for, checks the facts against primary sources and publishes clear, sourced explainers.
Spotted an error? Read our corrections policy or contact us. Last reviewed October 26, 2026.
Related stories
Student Loan Debt Collection: What Borrowers Should Know
Reports say collections on defaulted federal student loans could restart, which the Education Department disputes. What's official and what to do.
SSI November 2026 Payment Comes Oct. 30: What to Know
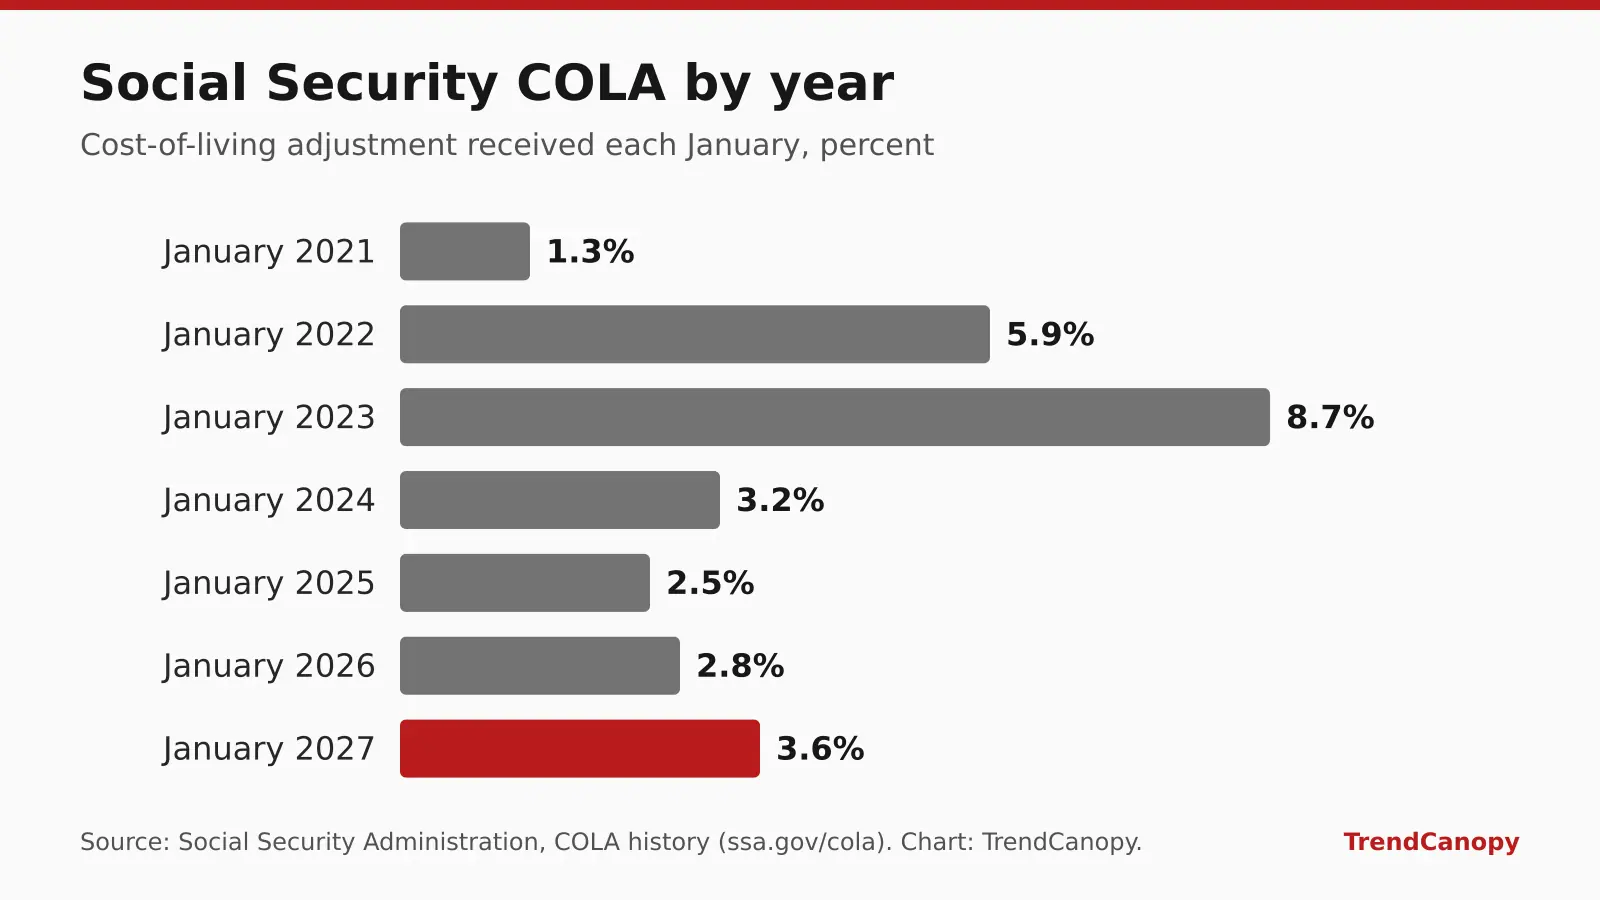
There's no SSI payment in November: it arrives early on Oct. 30. Here's the full payment schedule and what the 3.6% COLA for 2027 means for your check.
Anthropic IPO: Key Numbers From the Claude Maker's S-1
Anthropic filed to go public on Nasdaq as ANT. Here are the revenue, loss, compute deals and governance details from the S-1, and what happens next.